top of page
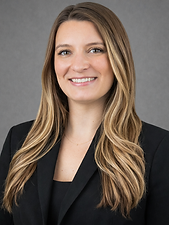
TESSA WAGONER
Wagoner headshot.png
ASSOCIATE
West Chester, PA
p: 610.436.4400 Ext. 1090
twagoner@buckleyllp.com

​​

Tessa Wagoner is an associate in the firm’s Litigation Practice Group. She represents municipalities, government entities, private individuals, and businesses in a variety of civil and appellate litigation matters.


Before joining the firm, Tessa practiced family law, where she managed complex divorce and custody cases through all stages of litigation, including discovery and trial. This experience developed her skills in case strategy, motion practice, and courtroom advocacy, which she now applies to a broad range of civil disputes.

​​​​

Areas of Practice

  • Commercial Litigation

  • Real Estate Litigation

  • Landlord Tenant Litigation

  • Appellate Litigation

  • Administrative and Regulatory Law 

​

Education

  • Florida State University College of Law, J.D., 2020

  • Florida State University College of Social Sciences, M.P.A., 2020

  • Florida State University, B.A., English and Political Science, 2015


Admissions

  • Supreme Court of New Jersey

  • Supreme Court of Pennsylvania

​​​​

Memberships

  • Chester County Bar Association

  • Burlington County Bar Association, Trustee

  • Burlington County Bar Foundation, Treasurer 

When a trust inherits a retirement account, one drafting choice can determine whether withdrawals must reach the beneficiary or can remain protected in trust.

​

A conduit trust requires distributions received from the retirement account to be paid promptly to, or for the benefit of, specified trust beneficiaries. An accumulation trust is a qualifying “see-through” trust that does not impose that pass-through requirement. These are federal retirement-distribution classifications, not two entirely different kinds of Pennsylvania trusts. Treas. Reg. § 1.401(a)(9)-4(f)(1)–(2).


Why the distinction matters


A conduit provision can simplify which trust beneficiaries count under the retirement-account rules, but it also means the trustee cannot retain account withdrawals for later use. An accumulation trust can preserve funds for a beneficiary who needs help managing money or protection from creditors. In exchange, remainder beneficiaries may count when determining the applicable payout rules; a poorly coordinated trust can produce an unexpectedly short distribution period. Treas. Reg. § 1.401(a)(9)-4(f)(3), (6).


Neither design automatically allows an IRA to remain intact for a beneficiary’s lifetime. For many non-spouse beneficiaries, the inherited account must be fully distributed by the end of the tenth year after death; annual withdrawals may also be required if the owner dies after the required beginning date. Special rules apply to surviving spouses, minor children of the owner, and certain disabled, chronically ill, or similarly aged beneficiaries. Treas. Reg. §§ 1.401(a)(9)-4(e), 1.401(a)(9)-5(d)–(e).


The question to ask: Is it more important to give the beneficiary access to each withdrawal, or to let a trustee retain and manage those withdrawals? Review the account designation, trust beneficiaries, distribution terms, and tax consequences together before naming a trust as beneficiary.

  • Facebook Social Icon
  • LinkedIn Social Icon
  • Twitter Social Icon
bottom of page